Hungary's new Wekerle Plusz mortgage programme launched on 28 October, replacing Otthon Start with different interest rates for newly built and existing homes.
Eligible buyers can borrow up to HUF 50 million over 25 years, with fixed interest of up to 3% for new homes and 5% for existing properties.
The programme is designed to help people buy a home to live in, rather than an investment property.
But who qualifies, and how much could you save?
Who Can Apply for Wekerle Plusz?
Applicants must be at least 18 and apply no later than their 45th birthday. Unlike Otthon Start, which had no upper age limit, Wekerle Plusz excludes older applicants.
You don't need to be married or have children, and there's no specific social-insurance-history requirement. However, banks will still assess your income and ability to repay the mortgage.
Unmarried couples can apply together, while parents or siblings may act as co-borrowers without acquiring ownership of the property.
Previous property ownership can affect eligibility. Generally, owning or having owned a 50% or greater share of another home is disqualifying, although exceptions apply to properties valued at no more than HUF 30 million.
The programme can only be used once and cannot be combined with another subsidised housing mortgage, such as CSOK Plusz.
How Much Deposit Do You Need?
The minimum deposit is 10%, although banks may require more depending on your financial circumstances and the property's valuation.
For example, buying a HUF 60 million Budapest apartment with a 10% deposit would require HUF 6 million in savings.
However, Wekerle Plusz has a maximum loan amount of HUF 50 million, meaning you'd actually need at least HUF 10 million of your own funds for that purchase, plus transaction costs.
Property prices are also capped.
Apartments cannot cost more than HUF 100 million, while the limit for houses is HUF 150 million. The purchase price must not exceed HUF 1.5 million per square metre.
That last restriction matters in Budapest, where smaller apartments in desirable neighbourhoods can exceed the square-metre ceiling even when their total price is below HUF 100 million.
How Much Will Wekerle Plusz Cost?
The biggest difference from Otthon Start is the interest rate on existing homes.
Previously, eligible buyers could obtain a fixed 3% mortgage regardless of whether the property was new or existing.
Under Wekerle Plusz, the 3% rate applies to new homes, while existing properties qualify for up to 5%.
For a HUF 50 million mortgage over 25 years, assuming interest rates of 3% and 5%, the difference is considerable.
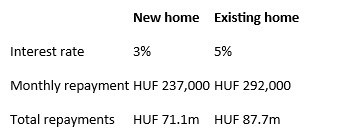
Illustrative standard monthly repayments, excluding fees.
That's approximately HUF 55,000 more every month for an existing property.
Of course, newly built apartments often cost more than older ones. A cheaper mortgage doesn't automatically mean a cheaper home.
Can You Rent Out the Property?
No, not during the first five years.
Buyers must move into the property and use it as their home. Renting it out during that period is prohibited.
This is particularly important for anyone considering buying a smaller apartment now and keeping it as an investment when they move elsewhere.
How Do You Apply?
Applications are made through participating banks, which may offer different rates and additional incentives.
There's also an important deadline for buyers who were already purchasing under Otthon Start.
Those who signed their purchase agreement by 31 October 2026 may still apply for the previous 3% mortgage until 15 November, subject to the transitional rules.
As 15 November falls on a Sunday, buyers should check their bank's submission deadline immediately.
For everyone else, Wekerle Plusz could provide a useful route into homeownership, particularly when purchasing a newly built property.
But the same principle applies to any subsidised mortgage: compare the total purchase cost, not just the interest rate.
A cheaper loan is helpful. Buying the right property at the right price matters more.